
A Google subsidiary registered a Swiss company on 31 July. It has not applied to drive anywhere. The decisions that will determine whether driverless fleets work in Zurich are being taken elsewhere: in parking rules and kerbside permits.
Five questions Zurich must answer
1. Has anything actually been approved? No, not for Waymo. Waymo Switzerland GmbH was entered in the commercial register on 31 July 2026 (capital CHF 100,000, c/o Google Switzerland, Gustav-Gull-Platz 1). But as of 10 August, it had not applied to the federal roads office (ASTRA) for any pilot operation. The only approval in Zurich belongs to someone else: WeRide holds an ASTRA permit and is testing with safety drivers in the Furttal, and Uber intends to offer the first driverless rides in Zurich by the end of 2026. The company everyone is discussing is not the one that is operating.
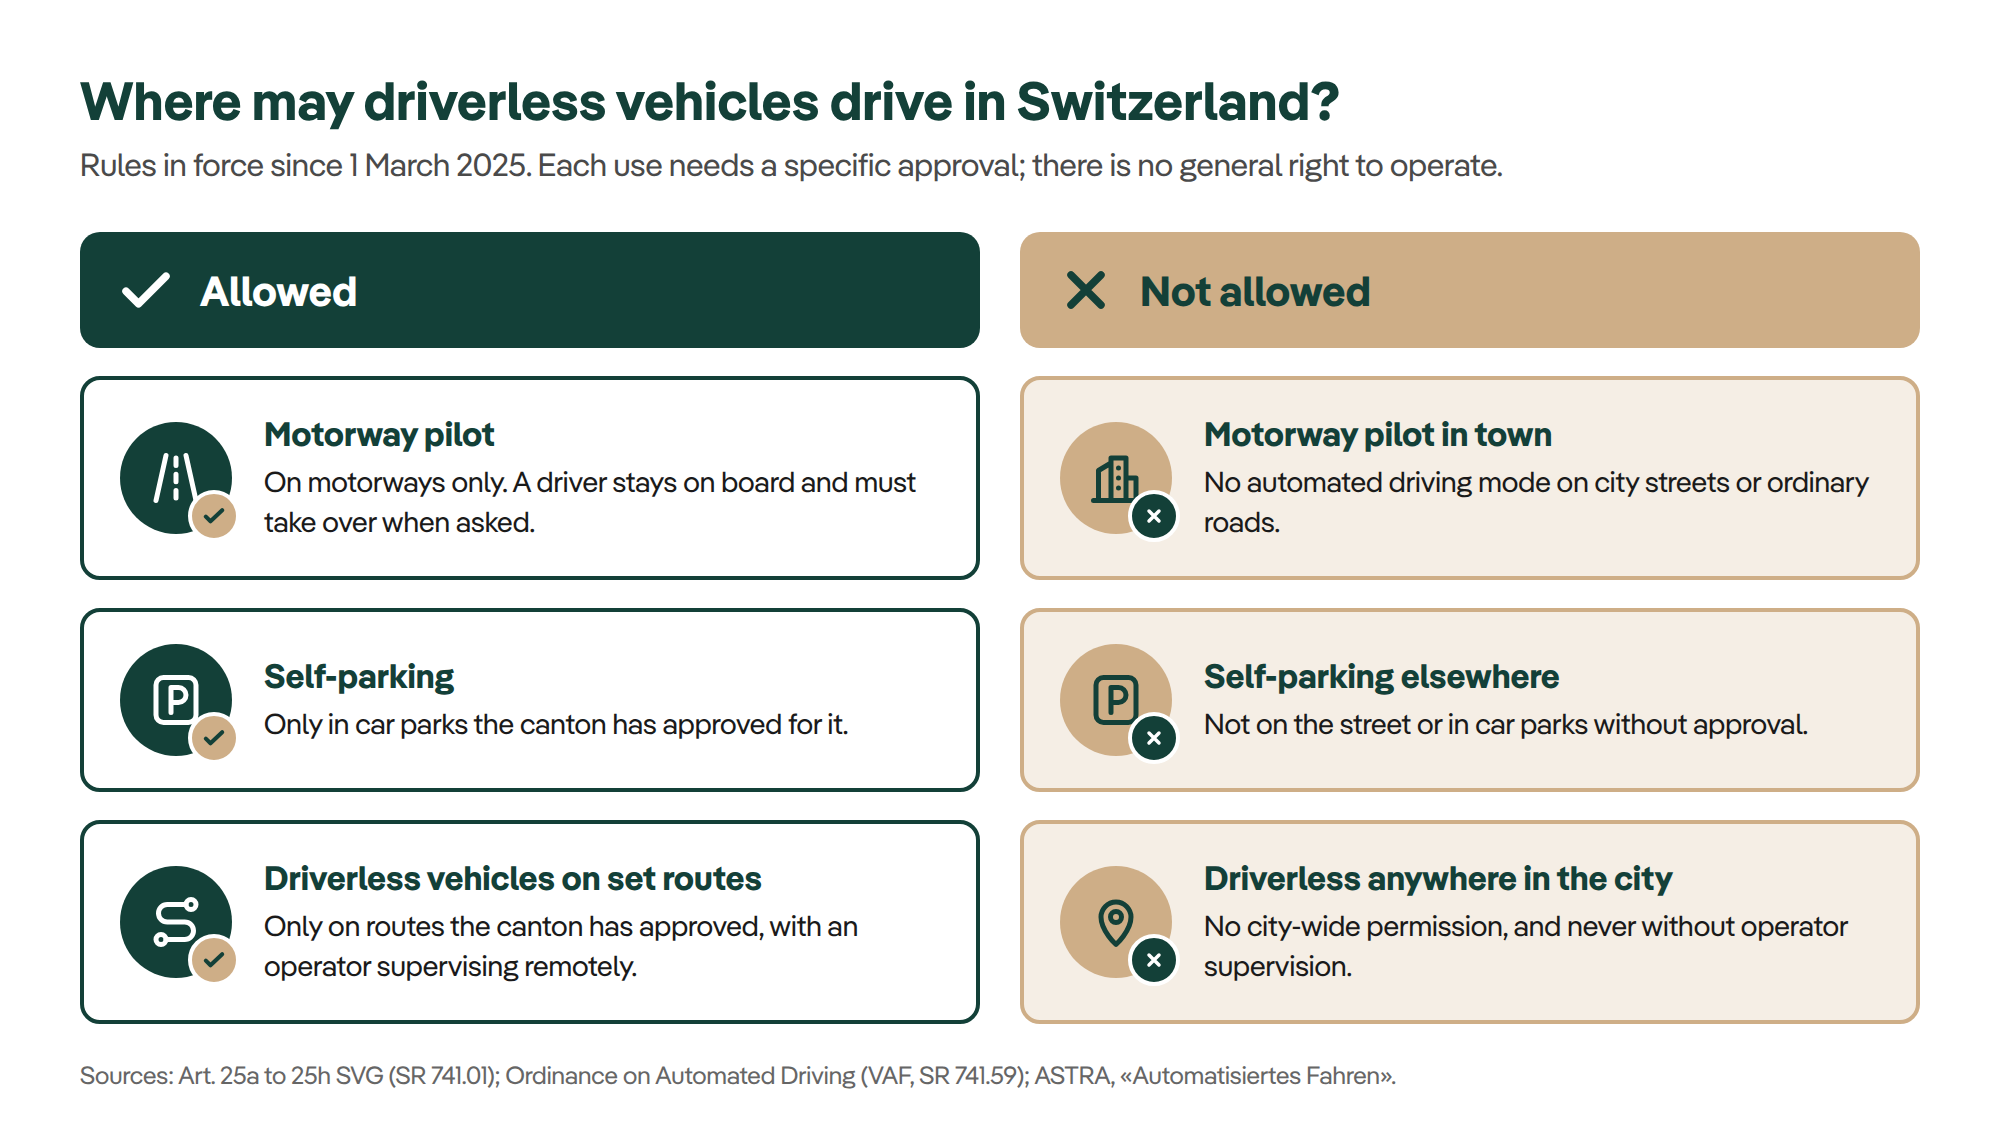
2. Where are driverless vehicles allowed to drive? Since 1 March 2025, Swiss law permits three things: a motorway pilot, driverless parking on approved sites, and driverless vehicles on routes a canton has expressly designated and an operator supervises. There is no city-wide right to operate. Twenty-six cantons draw twenty-six maps. This is not a technology approval. It is a permission slip, issued street by street.
3. Who controls the kerb? A robotaxi does not need a parking space. It needs somewhere to stop repeatedly, all day, in exactly the places where space is scarcest. Cities do hold the instruments: traffic orders, taxi stands, permits for the special use of public land. But those instruments were built for vehicles that stand still for hours, not for vehicles that halt for ninety seconds and leave. Zurich had 30,452 blue-zone spaces in April 2025, down from 31,173 at the end of 2022. That is on the order of 38 hectares of public land. Whoever decides where a driverless vehicle may stop decides who can run a service at all.
4. Does Zurich still need the parking the 1996 rules require? Zurich’s parking ordinance dates from 11 December 1996. It still requires one space per 120 m² of residential floor area, with a minimum of 10 to 70 per cent depending on transit quality. Each underground space consumes 26 to 30 m² and costs CHF 35,000 to 42,000 to build. In well-connected Swiss municipalities, average vacancy already runs at 29 per cent; individual developments reach 68. Note what that means. The rule is already misfiring, with or without driverless fleets. Autonomous vehicles do not create this problem. They put a deadline on it.

5. Who carries the risk when nobody is driving? Swiss law keeps liability with the vehicle’s keeper, regardless of fault, and the mandatory driving-mode recorder decides who pays afterwards. The open question is who the keeper is when the fleet sits in a Swiss company, the software is written in California, and the service is delivered by a third party. That is precisely the structure Waymo’s registered purpose contemplates.
Five things that need to happen now
1. Designate a supervised pilot corridor and publish the criteria. Not a decision to deploy, but a decision to learn what supervision actually costs.
2. Price the kerb. Stopping space should be allocated by permit and tariff, like any other scarce public asset, before it is allocated by whoever arrives first.
3. Re-open the 1996 parking ordinance on its own merits. A rule that produces 29 per cent vacancy needs revision whether or not a single robotaxi ever reaches Zurich.
4. Settle the keeper question in the contract between fleet owner, software supplier and operator, before the first accident, not after it.
5. Keep the safety debate and the space debate apart. Whether these vehicles drive well is an engineering question. Who controls the ground they stop on is not. Both deserve honest answers. Arguing one as the other produces neither.
At TND Universe, Future Urban Development brings spatial planning, green architecture, future mobility and the 15-minute city into a single advisory and investment perspective.
The Sky Becomes a Street: What You Need to Know About the Legal Status of Flying Taxis
Tomorrow's mobility is moving not only on the road, but increasingly in the air as well. Alongside self-driving cars, to which we have already dedicated a separate Insight (see Who is liable when the car drives itself?), so-called Volocopters, or electric flying taxis, symbolically represent the next major leap in urban mobility.
That this path is not without setbacks became apparent at the end of 2024: the German company Volocopter GmbH filed for insolvency proceedings with the Karlsruhe Local Court, and the court opened insolvency proceedings as requested by decision of 1 March 2025.[1]
And yet, only a few months later, the company returned to the certification track under new ownership and continues to push forward with the certification of its VoloCity flying taxi. According to an announcement dated 28 May 2026, experienced pilots, who are not test pilots, are for the first time worldwide flying an eVTOL aircraft under supervision in a real operating environment.[2] We therefore assume that flying taxis, or eVTOLs, will soon become a reality. The decisive question is: which legal groundwork needs to be in place before the first flying taxi takes off?
Do these taxis actually fly themselves, or is someone at the controls?
Not necessarily by themselves. Volocopter develops electrically powered aircraft that take off and land vertically, so-called eVTOLs (electric Vertical Take-Off and Landing aircraft). The best-known model, the VoloCity, is designed as an urban air taxi and is initially intended to be operated with a pilot on board; autonomous use is only planned as a later development step. According to the company's own statements, it has already completed more than 2,000 successful test flights and is working towards type certification by the European Union Aviation Safety Agency ("EASA").[3]
This distinction is central to the legal assessment. A piloted eVTOL is legally classified closer to classic manned aviation: there is a responsible person on board, to whom duties, qualification requirements and liability questions attach. An autonomously flying device, by contrast, shifts responsibility away from the person in the cockpit towards manufacturers, software providers and operators. Anyone speaking about flying taxis should therefore distinguish precisely in which operating mode they are travelling, as the legal consequences are fundamentally different.
Where do these aircraft actually land, and what does that mean legally?
A flying taxi is only as operational as the infrastructure supporting it. eVTOLs require their own take-off and landing sites, so-called vertiports. And this is precisely where a dense web of legal questions begins, reaching far beyond aviation law.
Anyone wishing to build a vertiport, for example on a rooftop, in a car park, or on a purpose-built terminal, finds themselves in the midst of building and planning law. Issues to be clarified include, among others: building permit procedures, noise protection, safety clearances, fire protection, access control, and integration into existing buildings. In addition, there are questions of spatial planning and neighbouring rights: anyone who sues over noise, shadowing, or safety concerns can significantly delay a project. The use of roof surfaces also raises questions of property and tenancy law. In short: before the first flying taxi lands, everything must be legally settled on the ground.
What rules apply, and what approvals are required?
In Europe, EASA is the central authority for eVTOLs. Because these aircraft cannot be clearly classified as either an aeroplane or a helicopter, EASA has created its own technical requirements: the "Special Condition for VTOL" ("SC-VTOL"), first published in July 2019.[4] This Special Condition sets out the airworthiness standards according to which a type certificate is granted for a small-category, passenger-carrying VTOL aircraft. Its scope covers aircraft with a maximum of nine seats and a maximum take-off mass of 3,175 kg.
For such a type certificate, the manufacturer must comprehensively demonstrate that its aircraft is safe, covering everything from the redundancy of critical systems, control, power supply and software, through to operating limits and failure scenarios. But that alone is not enough: commercial passenger transport additionally requires operational approvals. And as soon as a flying taxi crosses borders, questions arise regarding mutual recognition, operator authorisation, and regulatory oversight.
In Switzerland, the Federal Office of Civil Aviation ("FOCA") is the central supervisory authority. In the aviation sector, Switzerland largely adopts European rules and is closely integrated into European aviation law through the bilateral Air Transport Agreement. For unmanned aircraft, graduated categories and authorisation requirements already exist today, as does the concept of U-space airspaces.[5] FOCA defines these as designated areas within Swiss airspace in which digital services support the safe operation of drones. These building blocks form the foundation on which the future operation of manned flying taxis will be built.
Who actually owns the data generated by a flying taxi?
A modern eVTOL is a flying data generator. Every flight produces highly sensitive information: flight route and location data, passenger data, sensor, video or LiDAR data, as well as technical status and maintenance data, plus emergency and incident logs.
The seemingly simple question of "who owns this data?" is legally complex. This is because competing interests often exist in the same data sets: the operator wants to use it for fleet management, the manufacturer for product improvement, insurers for risk assessment, authorities for accident investigation, and the passenger has a right to the protection of their personal data. What therefore needs to be clarified, both contractually and under data protection law, is: who may collect, store, analyse and share which data? Who bears responsibility for its security? And how is personal data protected when movement profiles are recorded without gaps? Anyone who does not address these questions early risks disputes precisely when data is at its most valuable, or most sensitive.
And if something goes wrong, who is liable?
It is the question that looms over everything: who is liable if an eVTOL crashes? Legally, this remains largely unresolved, which makes it all the more important to think it through in advance.
Several, partly overlapping, lines of liability are conceivable: the operator's liability towards passengers as well as towards third parties on the ground; the manufacturer's product liability; liability for maintenance errors, software or sensor faults, and cyberattacks. In addition, there is the demanding question of recourse between insurers, operators, manufacturers, and suppliers, in other words, the question of who ultimately bears the economic burden of the damage at the end of the chain. At the same time, insurance coverage and potential compensation proceedings must be carefully defined. Precisely because many parties are involved in a single flight, the contractual allocation of risk in advance determines whether, in the event of damage, there is clarity or years of dispute.
Are Volocopters currently allowed to fly over roads in Switzerland?
In principle, yes; however, not yet in regular commercial operation. A Volocopter may only be operated in Switzerland if the aircraft and the operator are certified, the specific route is approved, and the take-off and landing infrastructure is authorised. The European legal framework for manned eVTOL aircraft exists in principle; however, its practical implementation in Switzerland, particularly with regard to vertiports, airspace integration, and approval procedures, has not yet been fully established.
Internationally, developments are further advanced: China has already granted initial approvals for commercial eVTOL passenger services,[6] while the United States has created specific regulatory frameworks for "powered-lift" or VTOL aircraft.[7]
The Swiss legislature must therefore establish clear and swift approval procedures, coordinate responsibilities between the federal government, cantons and municipalities, anchor vertiports in law, and regulate the integration of eVTOLs into existing airspace. At the same time, proportionate requirements regarding safety, noise, liability and infrastructure are needed. The goal must be a reliable and innovation-friendly legal framework that enables new air mobility concepts without lowering safety standards.
Conclusion
The future of air mobility is technically within reach, but legally anything but simple. Between type certification, vertiport approvals, data sovereignty and the allocation of liability lies a demanding interplay of aviation, construction, data protection and liability law. The Volocopter case also shows that even technological pioneers depend on viable legal and economic structures.
Anyone who wants to use, operate, insure or legally assess air mobility should clarify approvals, liability, data access and contractual risk allocation at an early stage, before the first flying taxi takes off. LINDEMANNLAW has in-depth knowledge, many years of experience and proven expertise in precisely these matters, and is your suitable partner if you want to create legal certainty in the field of air mobility.
[1]Insolvency proceedings opened against Volocopter GmbH - Karlsruhe Local Court
[2]ADAC Luftrettung Pilots Fly VoloCity with SimX Ground Station for the First Time
[4]Special Condition for VTOL and Means of Compliance | EASA
[6]First batch of national civil unmanned aircraft operation certificates for persons issued - Department News, Chinese government website
[7]Federal Register :: Integration of Powered-Lift: Pilot Certification and Operations; Miscellaneous Amendments Related to Rotorcraft and Airplanes
Building Permit Procedures in Switzerland: Why Fewer Rules Mean More Housing
More than a decade ago, the State Secretariat for Economic Affairs (SECO) put the regulatory costs of building construction alone at around 1.6 billion Swiss francs per year, almost 6 per cent of the construction volume[1], and the density of regulation has only grown since. Yet a convenient reflex has taken hold: Berne should solve the problem, and faster procedures would suffice. Both assumptions fall short. Anyone who reads the Federal Council’s report of 2 April 2026 on accelerating procedures in spatial planning and construction law[2] will see: under the Constitution, the federal government can deliver only part of the solution, and even where it does have jurisdiction, mere acceleration does little to address the underlying cause.
Who is responsible for building permit procedures and construction law in Switzerland?
Under Article 75 paragraph 1 of the Federal Constitution (Cst.), the Confederation has the power to lay down principles in the field of spatial planning. Implementation lies with the cantons, and construction law itself is essentially a cantonal matter. The Confederation regulates what is of national significance and must leave the cantons the greatest possible latitude in implementation, as their procedural sovereignty and organisational autonomy require (Article 46 paragraph 3 and Article 47 Cst.).[3] Every measure to accelerate procedures must be measured against this division of responsibilities.
Which acceleration measures has the Federal Council examined, and why does it reject most of them?
The Federal Council’s report carefully examines the most obvious proposals, from imposing costs on unsuccessful objectors to automatic approval once a deadline expires. For most of them, it concludes that they would encroach on cantonal procedural sovereignty or touch fundamental rights such as the right to be heard (Article 29 paragraph 2 Cst.) and the procedural guarantees of neighbours. This is not restraint born of convenience; it is the logical consequence of the constitutional allocation of powers.
«In this field, the Confederation can only do what the Constitution allows it to do: no more and no less.»
What can the Confederation actually deliver?
That leaves three or four measures for which the Confederation is genuinely competent: declaring housing construction a matter of national interest, narrowing standing to appeal, and restricting the grounds of appeal before the Federal Supreme Court. These are important but inherently limited levers: they concern proceedings before the Federal Supreme Court, the last of several instances, and not necessarily the place where the greatest delay arises. Zurich’s Seebahn-Höfe illustrate the point: the housing cooperatives ABZ and BEP have been planning the renewal of their late-1920s estates for some twenty years: 350 new cooperative apartments, housing for 1,000 instead of the current 500 residents.[4] After years of heritage-protection debates and the design-plan procedure, the project then faced a popular referendum in November 2025.[5] These delays lie outside what the Confederation may regulate: the challenge was never the procedure alone, but the sheer volume of substantive questions that had to be resolved.
Why does the body of rules keep growing regardless?
Two recent official examples show how quickly the rulebook is growing: the Special Building Ordinance I of the Canton of Zurich was expanded by roughly one third with the 2022 energy-law revision[6], and the latest revision of the Spatial Planning Act lengthens the revised articles by a similar order of magnitude.[7] Added to this is the cumulative effect of environmental, noise-protection, heritage-protection, climate and energy law at every level, federal, cantonal and municipal, each tightened independently of the others and overlapping in practice. Oliver Streiff, professor of public law at the Zurich University of Applied Sciences (ZHAW), describes this layering of rules from different fields of law as the core problem of today’s spatial planning and construction law.[8] That matches practical experience: a building application today passes through the building authority and the energy, noise, water-protection and transport agencies; each pursues its own specialised law, and every round of follow-up requests prolongs the procedure, regardless of how digital the form is or how far Berne narrows standing to appeal. Each revision is well founded on its own; taken together, they produce a body of rules that no developer can still keep track of, and that even a faster procedure does not make any smaller.
«More complex rules do not produce better buildings. They produce higher costs for the state, the authorities and developers, and they prevent housing that Switzerland urgently needs.»
What would actually help against the housing shortage?
Hans Wicki, president of the construction-industry umbrella organisation Bauenschweiz, puts it in a nutshell: real relief would come only from a substantial reduction of rules at every level and in every specialist field, not just in procedural law, and not just in Berne. The Canton of Zug is testing precisely this path with its «white zones»: building zones in which practically all customary building regulations would be suspended: no minimum distances, no height limits, with only safety-relevant standards remaining in force.[9] Jean-François Steiert, president of the Swiss Conference of Cantonal Directors of Public Works, Planning and Environmental Protection (BPUK), adds: the cantons must learn again to think free of norms. This is the right lever, but a legally delicate one: whoever abolishes rules must clarify who is liable if something goes wrong without boundary distances, because the strict liability of the owner of a structure under Article 58 of the Code of Obligations (CO) does not automatically fall away with them.[10] That is painstaking work for cantonal lawyers, not for the Federal Department of the Environment, Transport, Energy and Communications (DETEC).
Meanwhile, construction activity is declining: while a good 53,000 new apartments came onto the market in 2018, the most recent figure is around 43,000; with demand running at roughly 50,000 units per year, this opens up a gap of 7,000 to 10,000 apartments, year after year.[11] The decisive point is a finding that gets lost in the debate about speed: the complexity of the rules does not lead to better outcomes. It leads to a higher state quota, to higher costs in the building authorities that must cope with the ever-growing burden of review, and to higher costs for property developers, who ultimately finance it. Above all, it prevents urgently needed projects: first and foremost new housing, which is enormously important for Switzerland. The Confederation can use its constitutional framework and thereby makes an important, if limited, contribution. But the real reduction of rules can only be achieved by the Confederation and the cantons together, each within its own sphere of responsibility. More will only be built again when a construction project has to satisfy fewer rules, not merely the same rules faster.
Read the full article on Finanz und Wirtschaft (FuW): Regulierungswut: Schnellere Bauverfahren lösen die Wohnungsnot nicht
Sources:
[1] State Secretariat for Economic Affairs (SECO), Bericht über die Regulierungskosten (Report on Regulatory Costs), December 2013 (reference year 2011); cf. Kuster/Plaz/Curschellas, Regulierungskosten im Bereich Baurecht, Die Volkswirtschaft 1/2014: «Die Regulierungskosten des Hochbaus betragen für die Schweizer Wirtschaft im untersuchten Jahr 2011 insgesamt rund 1,6 Mrd. Franken oder knapp 6% des betrachteten Hochbauvolumens»
[2] Swiss Federal Council, report «Verfahrensbeschleunigung im Raumplanungs- und Baurecht» (Accelerating Procedures in Spatial Planning and Construction Law) of 2 April 2026 (adopted by the Federal Council on 22 April 2026)
[3] Federal Constitution of the Swiss Confederation of 18 April 1999 (Cst.; SR 101).
[4] Wohnbaugenossenschaften Zürich (Zurich housing cooperatives association), «Ja zum Gestaltungsplan ‹Seebahn-Höfe›»
[5] City of Zurich, media release «Volksreferendum gegen den privaten Gestaltungsplan ‹Seebahn-Höfe› zustande gekommen» of July 2025 (on municipal council resolution GR No. 2024/419 of 9 April 2025; popular vote of 30 November 2025)
[6] Special Building Ordinance I of the Canton of Zurich (BBV I; LS 700.21)
[7] Amendment of the Spatial Planning Act of 29 September 2023 (BBl 2023 2488), entering into force in stages since 2026
[8] This and the following quotations from Hans Wicki and Jean-François Steiert after: Andreas Valda, «Überbordende Baunormen erdrücken den Wohnungsbau», Bilanz of 6 July 2026
[9] «Kanton Zug: Fast ohne Regeln — weisse Zonen sollen Wohnungsnot bekämpfen», 20 Minuten of 7 April 2026
[10] Federal Act on the Amendment of the Swiss Civil Code (Part Five: Code of Obligations) of 30 March 1911 (CO; SR 220).
[11] Federal Department of Economic Affairs, Education and Research (EAER), Aktionsplan Wohnungsknappheit (Action Plan on Housing Shortage), round table of 13 February 2024, p. 5
Two permitting regimes, one grid: why Swiss nuclear licensing decides the cost
On 1 April 2026, Switzerland's Acceleration Decree came largely into force, shortening permitting and appeal procedures for large solar, wind and hydropower installations of national interest. Eleven weeks later, on 19 June, Parliament lifted the fifteen-year ban on new nuclear plants, and left the licensing architecture for those plants exactly where it was, adding one new condition at the entrance. Demand is heading from roughly 60 terawatt-hours today toward 68 to 81 by 2050. The country now runs two permitting regimes for the same grid: a fast lane for renewables, and for nuclear the old road, with a new toll booth at the start of it.
We have made this argument in two parts already: in June, that the winter supply gap makes this a sovereignty question rather than an energy-policy preference; in July, that Parliament legalised the plant while refusing the financing that would make it bankable. This is the third part, and the one nobody is debating: the procedure.
1. What does the nuclear licensing procedure actually require today?
Three stages, in a fixed order. The first is the framework licence, the Rahmenbewilligung, granted by the Federal Council under Art. 12 para. 1 of the Nuclear Energy Act (KEG), submitted to the Federal Assembly for approval, and subject to the optional referendum (Art. 48 paras. 1, 2 and 4 KEG). The Assembly is not a rubber stamp in one direction only: if the Council refuses and the Assembly declines to endorse that refusal, it instructs the Council to grant the licence (Art. 48 para. 3).
Only then come the construction and operating licences, both granted by the federal department (Art. 15 and 19 KEG). The construction licence presupposes a legally final framework licence and a project that complies with it (Art. 16 para. 2). These stages run under the Administrative Procedure Act; no cantonal permits are required, and the host canton is heard and may appeal if the department licenses over its objection (Art. 49 paras. 1, 3 and 4).
What Parliament changed in June was the prohibition, not the architecture. The two ban provisions were deleted, together with the cross-reference to them in Art. 12 para. 1, and a condition was added that a framework licence may be granted only where construction and operation are financially secured. The legislator declined to write a ban on federal participation into the law, and has not designed one either. The sequence a sponsor must fund is unchanged, and it now carries an additional hurdle placed before the first stage rather than after it.
2. Why is the first stage the most expensive risk?
Because duration and risk are not the same cost. Duration is a financing problem: more interest capitalised before the first franc of revenue. Painful, but calculable. Risk is an equity problem: the possibility that money already spent produces nothing at all, priced not in basis points but in the return an investor demands before committing anything.
Swiss nuclear licensing concentrates that second cost at precisely the wrong place, and it does so in the statute rather than in practice. Art. 12 para. 2 KEG provides that there is no legal entitlement to a framework licence. The Federal Office of Energy spells out the consequence in its own materials: a refusal must be accepted by the applicant without compensation. Set that beside the condition Parliament has now added, and the sequence reads as follows.
Secure the financing first, for a licence the law says you have no right to, and whose refusal costs the state nothing.
That is not a drafting oversight; it is a genuine circularity, and the most expensive single feature of the Swiss framework. A financing structure must be demonstrated in advance of a decision that is political in character, that no applicant can compel, and whose failure the applicant bears alone. Andreas Pautz, professor of nuclear engineering at EPFL and head of nuclear energy and safety research at the Paul Scherrer Institute, made the same point in the NZZ on 10 August: the dominant risks are planning risks, meaning objections and adverse popular votes, and investors will demand a premium for them.
The asymmetry runs through the timing too. The framework licence sets a deadline for filing the construction application and lapses if it is missed (Art. 14 para. 3 and Art. 68 para. 2 KEG). The clock runs against the sponsor; no comparable clock runs against the authorities.
3. What would dropping the framework licence cost in law?
Pautz proposes waiving it at the existing sites of Gösgen and Leibstadt: Western reactor designs are licensable in Switzerland in principle, those sites have demonstrated their suitability, and a two-stage procedure would, he argues, not offend Swiss democratic principles since the construction and operating licences remain. On the substance that is defensible; the technical assessment sits in those later stages.
But the stage is not only a technical filter. It is where the optional referendum sits (Art. 48 para. 4) and where participation is concentrated: application, expert opinions and cantonal positions lie open for three months, anyone may file objections, and parties may lodge formal opposition (Art. 45 and 46 KEG). Delete the stage and you delete a federal referendum right and the principal participation window with it. That engages the guarantee of access to a court under Art. 29a of the Federal Constitution and pushes objections downstream rather than removing them.
For capital, the consequence is counter-intuitive and decisive. Political risk does not disappear when the vote is removed; it relocates: to the construction licence, where the host canton keeps its own appeal right, and to a fresh popular initiative aimed at the outcome. A procedure that removes the ballot without putting finality in its place buys a few years and sells the certainty that made those years worth buying. That is our one departure from an otherwise sound analysis: keep the stage, and make the framework around it bankable.
4. What is actually missing, then?
Less than the acceleration rhetoric suggests, and something more specific. Two of the elements usually demanded already exist: preclusion, since whoever does not file opposition within the inspection period in the construction-licence procedure is excluded from the remainder of the proceedings (Art. 55 para. 1 KEG), and binding effect downward, since the construction licence requires a legally final framework licence and compliance with it (Art. 16 para. 2).
What is missing is narrower and more expensive. First, deadlines that bind the authorities, of the kind the Acceleration Decree now applies to large renewables projects: technology neutrality is not only about what may be built, but about how long the state may take to answer. Second, a rule on frustrated expenditure, since Art. 12 para. 2 places the entire loss of a failed framework procedure on the applicant, a defensible allocation when nobody was expected to apply and an expensive one now that Parliament wants applications. Third, sequencing: requiring proof of secured financing before a political decision no one can compel inverts the order in which infrastructure is actually financed. Fourth, an instrument rather than an unused option: a contract for difference, squared against the Electricity Supply Act, the Energy Act and the 2024 electricity package, treated openly as state aid, and negotiated with the Swiss–EU electricity file in view rather than around it. Pautz points to the same instrument, and to the Swedish combination of low-interest state loans and state co-ownership. Build cost per kilowatt matters, but next to these it is second order.
5. What has to be on the table before the vote?
The calendar is tighter than it looks. The Federal Chancellery reserves 28 February 2027 as the first federal voting date of that year, and the Federal Council settles at least four months beforehand which items actually go to the ballot. The substantive decisions therefore have to be visible this autumn, not in the new year: which risk-transfer instrument the Confederation contemplates; who absorbs construction-cost overrun; what becomes of sunk pre-development cost when a stage fails; and how the long tail is funded, meaning nuclear liability and the decommissioning and waste-disposal funds under Art. 77 KEG, bearing in mind that waste from any new plant would need its own framework licensing procedure for a repository.
On that last point the law is more revealing than the political debate. Art. 80 para. 4 KEG provides that where covering a shortfall is not economically bearable for those subject to the top-up obligation, the Federal Assembly decides whether and to what extent the Confederation contributes to the uncovered costs. The state already stands behind the back end of the nuclear balance sheet.
The other side of the argument
The alliance that launched the referendum on 30 June argues that new plants would deepen Switzerland's dependence on uranium imports from Russia, slow the expansion of renewables, and cost billions. Those objections deserve answers rather than dismissal.
Two are answerable. Dependence is not avoided by choosing renewables but relocated, to Chinese solar manufacturing and to the rare earths wind turbines require, as Pautz notes. And uranium can be stockpiled in a way gas cannot, from a supplier base running from Australia and Canada to Namibia and Kazakhstan. Cost is a reason to structure financing intelligently, not to rule out a technology. The third objection is the strongest: neither the financing architecture nor the procedural reform is on the ballot. On that we agree, and draw the opposite conclusion. A vote on an incomplete framework is an argument for completing the framework before the vote, not for rejecting the option and discovering in the winters after 2035 that the alternative was permanent import dependence.
Our view
Our position has not moved: Switzerland needs new nuclear. A firm domestic baseload on the order of 25 to 30 terawatt-hours, roughly today's nuclear share carried into a larger system, is what energy sovereignty actually looks like, and the designs that would supply it, including the small modular units now approaching deployment, are markedly safer than the plants they would replace. Pautz puts that comparison more sharply than we would: «Zehn weitere Jahre Betrieb von Altanlagen sind riskanter als ein neues AKW.»
Switzerland has built a fast lane for one set of technologies and left another on a road it has not resurfaced since 2003. The asymmetry inside the nuclear regime is sharper still: the Confederation has left the risk at the front of a project uncarried, where it is cheap, calculable and would move the financing cost that decides everything else, while the law already has it carrying residual risk at the back, where it is open-ended.
In July we wrote that permission without financing is symbolism rather than location policy. The same is true of permission without procedure. The correction is not to demolish a licensing stage and call it acceleration. It is to bind the authorities to deadlines as the law now binds the applicant, to say what happens to frustrated expenditure when a stage fails, to sequence the financing condition so that it follows the political decision instead of preceding it, and to legislate an instrument an investor can underwrite. Permission that cannot be relied upon is not an investment framework. Switzerland has one autumn to turn one into the other.
Dr. iur. Alexander Schiemenz is a co-founder of TND Universe, which creates, invests in and delivers real estate, mobility and energy solutions across their full lifecycle. If you are assessing an energy infrastructure position ahead of the vote, we advise on permitting risk, financing structure and the legal architecture that decides whether a permitted project is a bankable one.
Sources
1. Nuclear Energy Act (KEG), SR 732.1, consolidated text. Fedlex: https://www.fedlex.admin.ch/eli/cc/2004/723/de
2. Acceleration Decree for renewable energies, in force 1 April 2026. Federal Office for Spatial Development (ARE): https://www.are.admin.ch/de/beschleunigungserlass-erneuerbare-energien
3. Indirect counter-proposal to the "Blackout stoppen" initiative, explanatory report (provisions deleted; no compensation on refusal; separate licensing procedure for a repository). SFOE/DETEC: https://www.newsd.admin.ch/newsd/message/attachments/91232.pdf
4. Federal Council message of 13 August 2025 on the indirect counter-proposal. admin.ch: https://www.admin.ch/de/newnsb/GIECKzWVs6ZX6W1ba4i6X
5. UREK-S of 20 January 2026, recommendation to lift the framework-licence ban. Parliamentary Services: https://www.parlament.ch/press-releases/Pages/mm-urek-s-2026-01-20.aspx?lang=1031
6. Council of States decision of 11 March 2026, financing condition. Parliamentary Services: https://www.parlament.ch/de/services/news/Seiten/2026/20260311124425486194158159026_bsd112.aspx
7. Launch of the referendum on 30 June 2026 and the alliance's arguments. Federal Chancellery media announcement: https://www.admin.ch/de/medienkonferenz-nein-zu-neuen-akw-lancierung-des-referendums-gegen-das-atom-gesetz
8. Reserved federal voting dates; Federal Council fixes the agenda at least four months in advance. Federal Chancellery: https://www.bk.admin.ch/ch/d/pore/va/vab_1_3_3_1.html
9. Interview with Andreas Pautz (EPFL / Paul Scherrer Institute), Neue Zürcher Zeitung, 10 August 2026
10. TND Universe, "A Permit Is Not a Power Plant" (13 July 2026): /news/a-permit-is-not-a-power-plant-switzerlands-half-decision-on-new-nuclear
11. TND Universe, "Sovereignty, supply gaps, SMRs" (11 June 2026): /news/five-five-sovereignty-supply-gaps-smrs-what-needs-to-be-understood-before-switzerland-decides-on-nuclear
Who is liable when the car steers itself?
The self-driving car is no longer science fiction, it is already rolling on Swiss roads. Since 1 March 2025, Switzerland has had, with the Ordinance on Automated Driving (VAF)[1], a clear legal framework that for the first time expressly permits motorway pilots, driverless vehicles and automated parking. For once, the legislator was even faster than the industry; while the legal framework is in place, there are currently no series-production vehicles with an approved automation system on the market.
Regulation is developing rapidly not only in Switzerland but worldwide. EU directives, EU regulations and UNECE regulations are also binding on Switzerland. These international requirements ensure the technical harmonisation of road vehicles and promote road safety, environmental protection and the free movement of goods.
The following bodies of rules are particularly relevant for automated driving:
- Regulation (EU) 2022/1426[1] (in conjunction with Regulation (EU) 2019/2144[2] and Delegated Regulation (EU) 2022/2236[3]) on the type-approval of the automated driving system (ADS) of fully automated vehicles;
- the UNECE Regulations on cybersecurity (No. 155)[4], software updates (No. 156)[5], automated lane-keeping systems (No. 157)[6] and driver assistance systems (No. 171)[7]; and
- the Vienna Convention of 8 November 1968 on Road Traffic (SR 0.741.10)[8], in particular on the question of whether a driver must be present.
For companies, investors, fleet operators and mobility service providers, this new legal framework opens up considerable opportunities, but also demanding legal questions. We answer five of them below.
When does a car actually drive «by itself»?
Not every vehicle with an assistance system is an automated vehicle. The internationally established SAE J3016 standard distinguishes six levels of automation, from Level 0 to Level 5:
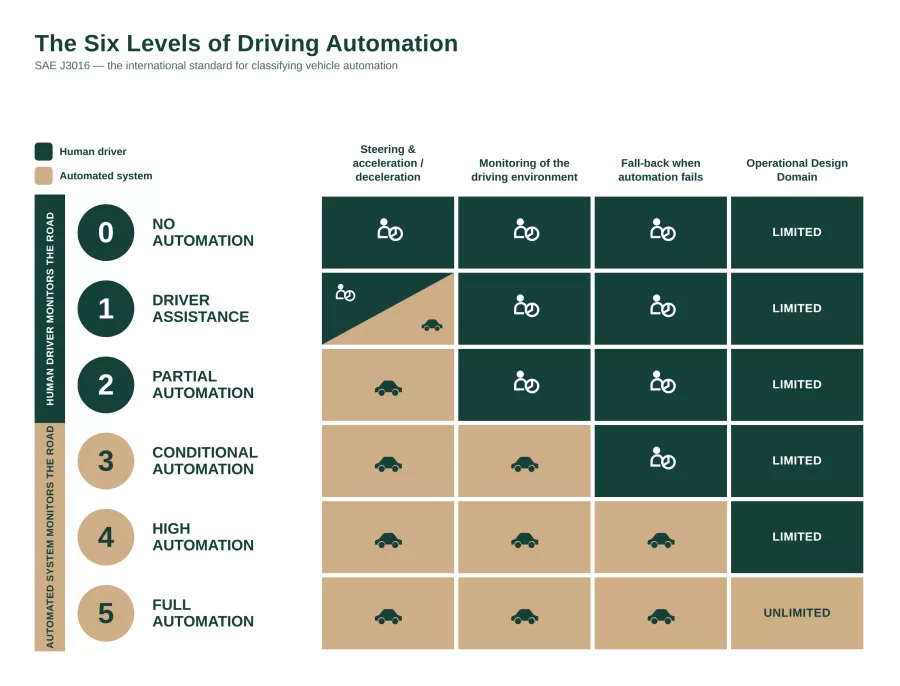
Automated driving only begins at Level 3: vehicles that can take over the driving tasks permanently and comprehensively, at least under certain conditions. Only the highest level, Level 5, is truly «autonomous» in the literal sense; today's systems technically reach a maximum of Level 3.
In Switzerland, three specific use cases have been permitted since March 2025:
1. the motorway pilot: drivers may take their hands off the wheel on motorways, but must be able to intervene again at any time when prompted by the system;
2. automated parking without a driver present in car parks signposted for this purpose; and
3. the operation of driverless vehicles on routes approved by the authorities.
What approvals and technical requirements are needed?
Vehicles with an automation system must meet special requirements going beyond the general requirements in order to be admitted. Under the general requirements set out in Art. 3 VAF, the system must guide the vehicle in the longitudinal and lateral directions, be intuitively deactivatable at any time, have functions for accident avoidance as well as safeguards against unlawful third-party interference, and master all traffic scenarios in accordance with recognised international rules. During operation, the system must take over the operation of the vehicle continuously, comprehensively and reliably, comply with all relevant traffic rules, detect technical malfunctions and indicate the need for human intervention with a sufficient time reserve (Art. 3 paras. 2 and 3 VAF).
The driving-mode memory is central (Art. 7 VAF): automated vehicles must record certain events (such as emergency manoeuvres, collisions or technical malfunctions), together with data elements such as the type of event, time stamp and position. In addition, for the entire supported operating period, manufacturers must hold valid certificates from a national type-approval authority for the management systems for cybersecurity (UN Regulation No. 155), software updates (UN Regulation No. 156) and safety for driverless vehicles under Regulation (EU) 2022/1426 (Art. 8 VAF).
Switzerland's approach to type-approval is noteworthy (Art. 11 et seq. VAF): Switzerland currently refrains from having its own type-approval provisions and instead recognises the requirements of the EU and UNECE. Automated vehicles that are to be admitted here therefore require a foreign type-approval; ASTRA (the Federal Roads Office) merely carries out random conformity checks. Manufacturers and importers of driverless vehicles must report safety-relevant incidents to ASTRA, and ASTRA may declare new provisions applicable to vehicles that have already been admitted, for instance in the event of a hacking attack (Art. 6 VAF). Operation is thus strongly tied to approval and operating conditions: driverless vehicles require cantonally approved routes and must be supervised by operators from a control centre.
What happens to the recorded data?
Automated vehicles must be equipped with a driving-mode memory (colloquially a «black box») that records events such as the start and end of emergency manoeuvres, system failures, collisions, and the activation and deactivation of the automation system. The processing of this data is subject to strict conditions: under Art. 25g para. 3 SVG, the data may be read out and processed by the competent police, judicial and administrative authorities exclusively for the purpose of investigating accidents or assessing traffic-rule violations.
Manufacturers and importers of driverless vehicles and of vehicles with an automated parking system must report safety-relevant incidents to ASTRA and must agree with the vehicle keepers or the operators of approved parking areas on how the necessary information is to be obtained. Operators of car parks offering automated parking must also notify the police in the event of an accident. Data protection and controlled access to this driving data are therefore a central and legally sensitive building block of the new regime, especially for fleet operators and mobility providers that process large volumes of data.
Who is liable when the software steers?
If a person is harmed in an accident, in principle the insurer provides compensation first; only afterwards is it clarified who was actually responsible. The key point: despite technical autonomy, the vehicle keeper remains liable under the causal liability of Art. 58 SVG, a no-fault, risk-based liability. In an accident involving an automated vehicle, three levels of causation ultimately come into consideration:
- the manufacturer (for instance in the case of software or sensor faults under the Product Liability Act);
- the driver (if they were steering themselves at the time of the accident); or
- the keeper (for example in the case of inadequate maintenance).
Legally, this is so intriguing because the allocation of risk shifts noticeably: from the driver to the system function, from the classic driving error to a product, software or maintenance defect, from pure SVG liability towards questions of recourse, product liability and evidence, and from the visible course of the accident towards the evaluation of technical data. Whether the human or the system was in control at the time of the accident can be traced through the driving-mode memory. The evaluation of this data thus becomes decisive for asserting recourse claims. For manufacturers, importers and operators this means a potentially higher liability risk; and for all parties involved, the urgent need to settle the contractual allocation of risk cleanly at an early stage.
What role does cybersecurity play?
A self-driving vehicle is essentially a rolling computer, and thus a potential target for cyberattacks. Cybersecurity is therefore not merely a peripheral technical issue, but a load-bearing element of the approval regime. Manufacturers must hold valid certificates for their cybersecurity management system under UN Regulation No. 155 and for their software-update management system under UN Regulation No. 156, and this for the entire supported operating period of the vehicle. The aim is to prevent external attacks and to avoid failures and malfunctions.
The regulation also takes account of this risk dynamically: ASTRA may even declare new provisions applicable retrospectively to vehicles that have already been approved and put into circulation, for example when certain vehicle types are affected by a hacking attack (Art. 6 VAF). For companies, this means: cybersecurity is not a one-off approval hurdle, but an ongoing legal and organisational obligation throughout the entire life cycle of the vehicle.
Conclusion
Self-driving vehicles will fundamentally change mobility, and in Switzerland they are already a reality. In Zurich's Furttal, the Swiss Transit Lab, the cantons of Zurich and Aargau and the SBB (Swiss Federal Railways) are deploying self-driving vehicles in the «iamo» pilot project (intelligent automated mobility); following approval by ASTRA, they are for the first time travelling in automated mode on public roads, and the public should be able to use the service in the first half of 2026[10]. Level 5 vehicles do not yet exist, but development is advancing quickly, and it is foreseeable that full automation will follow in the not-too-distant future.
Automated mobility is opening a new frontier of opportunity for investors, developers and operators, and with it a set of questions that deserve early attention: approvals and admission, liability and recourse risks, data access and data protection, and the allocation of risk between manufacturers, importers, operators and users. Addressing these questions early is what turns a promising technology into a sound, long-term investment.
This is precisely where TND Universe adds value. With expertise spanning real estate, mobility and energy, and a commitment to sustainable development, transparency and long-term investment integrity, we help clients evaluate, structure and realise automated-mobility opportunities across their full lifecycle, from initial due diligence through to operation and value creation.
Talk to us. Whether you are looking to invest in, develop or operate automated-mobility solutions, our team can help you navigate the risks and unlock the opportunities of this fast-evolving field. Contact us for a non-binding initial conversation.
Sources
[1] AS 2025 50 - Ordinance of 13 December 2024 on Automated Driving (VAF) | Fedlex
[2] Implementing Regulation - 2022/1426 - EN - EUR-Lex
[3] Regulation - 2019/2144 - EN - EUR-Lex
[4] Delegated regulation - 2022/2236 - EN - EUR-Lex
[5] UN Regulation No. 155 — Uniform provisions concerning the approval of vehicles with regard to cyber security and cyber security management system [2025/5]
[6] UN Regulation No. 156 - Software update and software update management system | UNECE
[7] UN Regulation No. 157 - Automated Lane Keeping Systems (ALKS) | UNECE
[8] UN Regulation No. 171 — Uniform provisions concerning the approval of motor vehicles with regard to Driver Control Assistance Systems (DCAS) [2024/2689]
[9] SR 0.741.10 - Convention of 8 November 1968 on Road Traffic (with annexes) | Fedlex
[10] iamo – intelligent automated mobility; Pilot project «iamo» on automated driving in the Furttal | Canton of Zurich